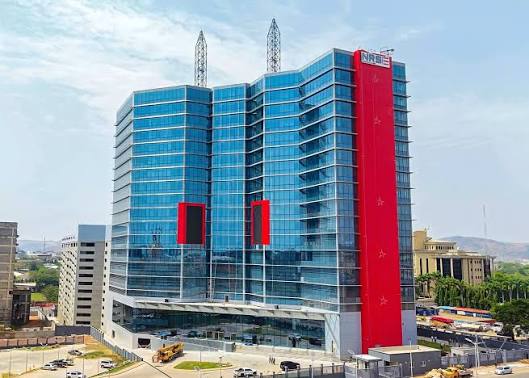
The House of Representatives Public Accounts Committee (PAC) has intervened in a dispute between the Nigeria Revenue Service (NRS) and the Tertiary Education Trust Fund (TETFund) over the deduction of N123.48 billion as a four per cent cost of collection on education tax.
The dispute arose during the committee’s ongoing examination of audit queries relating to revenue collections and remittances, where both agencies presented conflicting interpretations of the legal provisions governing the deductions.
The hearing, chaired by Rep. Bamidele Salam, featured the NRS, represented by its Executive Director, Shettima Tamadi, and TETFund, represented by its Director of Finance and Accounts, Dr Gloria Olotu.
The committee was informed that the Auditor-General had identified discrepancies between the Education Tax collected by the NRS (formerly known as the Federal Inland Revenue Service, FIRS) and the amount remitted to TETFund, raising questions about the four per cent cost-of-collection deductions.
Presenting TETFund’s position, Olotu argued that the four per cent deduction should apply only to non-oil revenue and not the entire education tax collected from companies in both the oil and non-oil sectors.
She explained that following the Auditor-General’s observation, the Fund reviewed the deductions and discovered that the NRS had applied the charge to the entire Education Tax collection without excluding the oil-sector component.
According to her, an examination of the NRS’s own revenue breakdown showed that excess deductions between 2012 and 2024 amounted to N123,486,953,796.24.
Olotu said TETFund had written several letters to the revenue agency seeking a refund but had yet to receive the money.
However, defending the deductions, the NRS representative insisted that the agency was not liable to refund any amount to the Fund.
He relied on Sections 15A and 69 of the NRS Act, arguing that the law defines non-oil revenue as all revenue other than proceeds from Petroleum Profits Tax (PPT).
On that basis, he maintained that education tax paid by oil companies does not qualify as Petroleum Profits Tax and is therefore subject to the four per cent cost-of-collection deduction.
The NRS official further explained that oil companies pay Petroleum Profits Tax separately, adding that the agency does not deduct collection charges from such payments.
Following the conflicting interpretations, the committee observed that although the NRS’s position appeared straightforward from an ordinary reading of the relevant provision, the matter required an authoritative legal interpretation.
TETFund informed the lawmakers that it had previously sought the Attorney-General of the Federation’s (AGF) opinion on the dispute and undertook to forward the response to the committee.
The committee, however, resolved to independently obtain the AGF’s legal opinion before determining the appropriate course of action.
It noted that while the law appeared to define non-oil revenue, the disagreement over whether Education Tax paid by oil companies falls within that category required further clarification.
The hearing was subsequently adjourned pending the submission of written positions requested from TETFund and the Attorney-General’s legal advice.